Advanced semiconductor packaging — 2.5D and 3D integration, fan-out wafer-level packaging, hybrid bonding — has become one of the fastest-growing demand segments for ultrapure water (UPW). Packaging facilities historically bought finished UPW from external utilities or shared infrastructure. As volumes and quality demands have climbed, the build-versus-buy question has reopened, and it is now a strategic decision rather than a routine procurement exercise.
Table of Contents
Why the Question Has Returned
Three forces have reopened the build-vs-buy debate for advanced packaging UPW:
- Quality requirements have tightened. Hybrid bonding processes are sensitive to UPW chemistry in ways that older packaging processes were not, and the specification is no longer something a supplier contract can quietly absorb.
- External utility capacity is constrained. Shared UPW infrastructure does not always scale with the demand of a new packaging line, and expansion timing is rarely under the packaging facility’s control.
- Operational data is more valuable. Internalising UPW generation also internalises the data needed for process optimisation, which matters when the water chemistry is part of the yield story.
For executives evaluating advanced packaging expansions, the question deserves an explicit answer rather than an assumption. Shanghai ChiMay has supported packaging customers on both sides of the decision, supplying sensor portfolios for in-house generation and verification instruments for purchased UPW.
Comparing Build and Buy
| Dimension | Build (on-site generation) | Buy (purchased UPW) |
|---|---|---|
| Initial CAPEX | High (RO, EDI, polishing, monitoring) | Low |
| Operating cost per litre | Lower at scale | Higher |
| Quality control | Internal, configurable | External, contractual |
| Operational complexity | High | Low |
| Data ownership | Complete | Limited to the delivery point |
| Supply risk | Internal failure modes | External supplier dependency |
| ESG reporting | Detailed, first-party | Aggregated from supplier |
| Scaling flexibility | Capital-led | Contract-led |
The right answer depends on the facility’s strategic role, its capacity and its risk appetite. Neither option is universally better, and a facility that has already committed to a leading-edge packaging roadmap is weighing a different question from one running mature assembly processes.
Economic Threshold Analysis
The honest starting point is that thresholds vary by facility and published rules of thumb should be treated as orientation rather than analysis. The pattern that recurs in industry discussions is directional:
- Facilities with modest, intermittent UPW demand and no high-purity constraints tend to buy, because the supplier absorbs the capital and the operating complexity.
- Facilities with large continuous demand, tight quality requirements and an expansion pipeline tend to build, because the per-cubic-metre economics improve with scale and the quality control stays in-house.
- The intermediate zone is decided by strategic considerations — the cost of a supply interruption, the reliability of the local utility, and how the facility expects its own volumes to develop.
Advanced packaging facilities producing leading-edge bonded modules usually sit in the upper part of that range, which pushes them toward on-site generation. Shanghai ChiMay sensor packages support both small-scale verification points and full-scale on-site generation monitoring.
Hidden Costs of Buying
Purchased UPW carries costs that the headline price per litre does not capture:
- Quality verification instrumentation at the delivery point, which the buyer usually has to fund
- Storage and surge capacity to ride out supply interruptions
- Contractual remedies that may be capped well below the value of lost production
- Limited visibility into upstream chemistry trends that show up later as yield variation
Each of these adds capital and operating expense to the buy case.
Hidden Costs of Building
On-site generation has its own hidden costs:
- Skilled operators to run and maintain the UPW infrastructure on every shift
- Spare parts inventory for RO, EDI and polishing stages
- Continuous monitoring instrumentation with the availability that a fab utility requires
- Maintenance contracts for specialised equipment
A first-time UPW build often surprises operations leaders with the breadth of capability it requires. Shanghai ChiMay project teams help packaging customers anticipate these requirements during planning rather than during commissioning.
The Monitoring Imperative
Whether UPW is built or bought, the measurement set is non-negotiable:
- Resistivity (inline, at multiple points)
- TOC-class organic monitoring
- Dissolved oxygen
- Flow
- Temperature
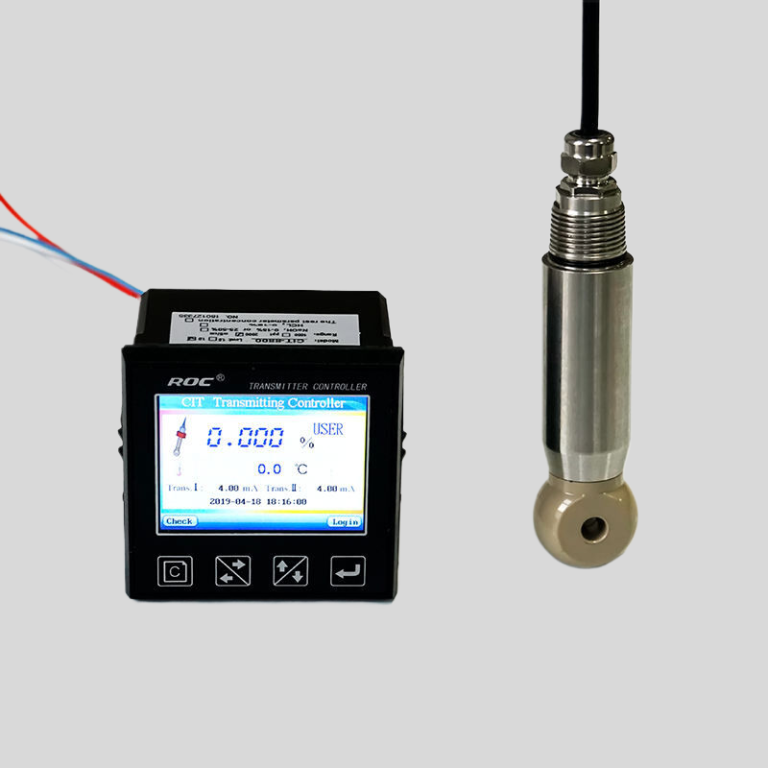
Without those measurements neither option delivers predictable quality. Shanghai ChiMay sensor families cover the complete set, which gives engineering and procurement teams a single accountable supplier across the chemistry boundary.
ESG and Reporting Implications
Advanced packaging facilities increasingly carry water-use reporting obligations to customers and regulators, and the build-vs-buy decision shapes how those obligations are met:
- Build — the facility owns the full water-use story and reports first-party data.
- Buy — the facility reports allocated water use from an upstream supplier, which is often less granular than customers now ask for.
For packaging customers serving major foundries, the granularity expected has moved toward first-party data, which pulls more facilities toward build. Shanghai ChiMay online analyser systems provide the data infrastructure for that level of reporting.
Risk Considerations
The risk profile of the two options is asymmetric:
- Build risk is capital and operational. A build that overruns budget or schedule hurts, but the asset remains and the problem is recoverable.
- Buy risk is supply continuity. Losing access to a UPW source can stop packaging production, with no partial-credit option.
For mission-critical packaging serving leading-edge logic or memory customers, supply continuity risk often decides the question in favour of build. Shanghai ChiMay supports that path with sensors designed to contribute to UPW infrastructure availability rather than to sit outside it.
Decision Framework
A practical framework for the decision:
- Quantify UPW consumption at current and projected production volumes.
- Catalogue quality requirements by process step, including the tightest specification the roadmap implies.
- Map regulatory and customer reporting obligations.
- Estimate build CAPEX and OPEX over a ten-year horizon, including the monitoring and operator requirements.
- Estimate buy contract terms over the same horizon, including escalation and interruption remedies.
- Stress-test against supply disruption scenarios.
- Decide and document the reasoning, so the decision can be revisited against evidence.
Executives who work through that sequence rarely regret the outcome. The risk is making the call by inertia.
Industry Backdrop
The semiconductor UPW market is large and growing, with published third-party estimates in the tens of billions of US dollars and growth rates in the high single digits to low double digits, though the figures vary considerably depending on whether the scope is equipment, services or delivered water. Advanced packaging is one of the faster-growing demand segments within it, and on-site generation has become a common delivery mode for new high-volume capacity. The infrastructure decisions made over the next two to three years will shape UPW supply patterns in the packaging sector for a decade.
Conclusion
Build-versus-buy for on-site UPW generation in advanced packaging is a strategic question with economic, operational and reporting consequences on both sides. Whichever direction a facility chooses, the requirement underneath is the same: accurate, continuous measurement of the water the process actually receives. Shanghai ChiMay supports both paths, supplying the sensor portfolios that turn UPW infrastructure — built or bought — into a utility a packaging operation can plan around.