IoT-integrated sensors have moved from early-adopter territory into the mainstream of new water-quality monitoring deployments. Five years ago they were the exception; today they are the default expectation for most new projects. The adoption curve has crossed the majority threshold. For utilities and industrial water operators that have not yet made significant investments in IoT sensor infrastructure, the strategic question is no longer “should we?” but “how do we catch up without repeating our peers’ mistakes?” This article addresses that question at the executive level.
Table of Contents
Reading the Adoption Curve
Adoption curves past the majority inflection point exhibit specific market characteristics that late movers should understand:
- Technology has consolidated — winners have emerged among sensor form factors, protocols, and cloud platforms.
- Prices are compressed — unit economics favor buyers, but service and integration costs remain significant.
- Best practices are documented — early-adopter case studies expose common failure modes.
- Vendor consolidation is ongoing — merger and acquisition activity is reshaping vendor landscapes.
- Talent is scarcer — engineers experienced with IoT water deployments are in high demand.
Late movers who understand these dynamics can extract genuine strategic value. Those who ignore them risk repeating early-adopter mistakes with even less time to correct course.
Strategy 1: Targeted Leapfrog
Rather than modernize the entire sensor fleet, the utility selects a small number of high-value use cases and deploys state-of-the-art IoT sensor and analytics infrastructure to serve them. Typical use cases include:
- Non-revenue water reduction in a specific district.
- Real-time PFAS breakthrough monitoring at a critical intake.
- Chemical dosing optimization at a treatment plant.
- Aging asset monitoring for a specific pipeline segment.
Strengths: fast time to value, contained cost, clear ROI story, controlled risk.
Weaknesses: does not build utility-wide capability, may create data silos, difficult to scale.
Best fit for utilities with strong technical staff and a specific operational pain point that justifies the investment.
Strategy 2: Phased Modernization
The utility develops a multi-year modernization roadmap that replaces legacy sensors on a scheduled basis, coordinated with routine maintenance cycles. Typical phasing:
- Year 1: Priority zones (treatment plants, critical intake, distribution nodes).
- Years 2-3: Secondary zones (elevated tanks, pump stations, monitored branches).
- Years 4-5: Long-tail assets (residential meters, isolated remote points).
Strengths: manageable capital pace, aligned with maintenance cycles, builds internal capability progressively.
Weaknesses: slower payoff, integration debt persists through the transition, requires disciplined execution.
Best fit for large utilities with long infrastructure horizons and rate-regulated capital planning.
Strategy 3: Hybrid Partnership
The utility engages an integrated service partner — vendor, engineering consultancy, or joint venture — to deploy and operate the IoT sensor and analytics infrastructure under a managed-service arrangement. The utility retains data ownership and strategic decisions; the partner handles installation, integration, and operations.
Strengths: fastest capability build, transfers execution risk, avoids in-house hiring gap.
Weaknesses: higher long-term operating cost, vendor lock-in exposure, must guard against loss of institutional knowledge.
Best fit for utilities lacking internal digital-transformation talent or facing a compressed regulatory timeline.
Strategy Comparison
| Dimension | Targeted Leapfrog | Phased Modernization | Hybrid Partnership |
|---|---|---|---|
| Time to first value | 6-12 months | 18-24 months | 9-15 months |
| Total 10-year cost | Lowest | Medium | Highest |
| In-house capability built | Modest | Strong | Limited |
| Risk profile | Contained | Distributed | Transferred |
| Best when | Specific pain point | Rate-base capital cycle | Talent shortage |
Common Late-Mover Traps
Late movers should avoid five recurring mistakes:
- Wholesale replacement without a plan — replacing thousands of sensors in a compressed schedule creates integration debt without delivering operational value.
- Selecting last generation technology at deep discounts — the initial savings are eroded by shorter useful life and platform compatibility gaps.
- Under-investing in data foundation — installing IoT sensors without upgrading data historians, cybersecurity, and analytics capabilities wastes the sensor investment.
- Copying an early adopter’s architecture — architectures optimized for the technology of 2020 may not fit current realities.
- Under-communicating with rate-payers and regulators — the political dimension of digital transformation is real, especially for public utilities.
The Data Governance Imperative
Regardless of chosen strategy, late movers should establish data governance policies before large sensor deployments begin. Governance elements include:
- Data ownership and access controls.
- Retention and archival policies.
- Cybersecurity baselines aligned with IEC 62443.
- Third-party data-sharing agreements.
- Regulatory disclosure procedures.
Retrofitting governance after data infrastructure is deployed is significantly more expensive than establishing it upfront.
How Shanghai ChiMay Supports Each Strategy
Shanghai ChiMay water quality analyzer products supply the sensor layer that any of the three strategies require:
- Targeted leapfrog — deploy 4-in-1 multi-parameter sensors and residual chlorine transmitters at the specific high-value monitoring points.
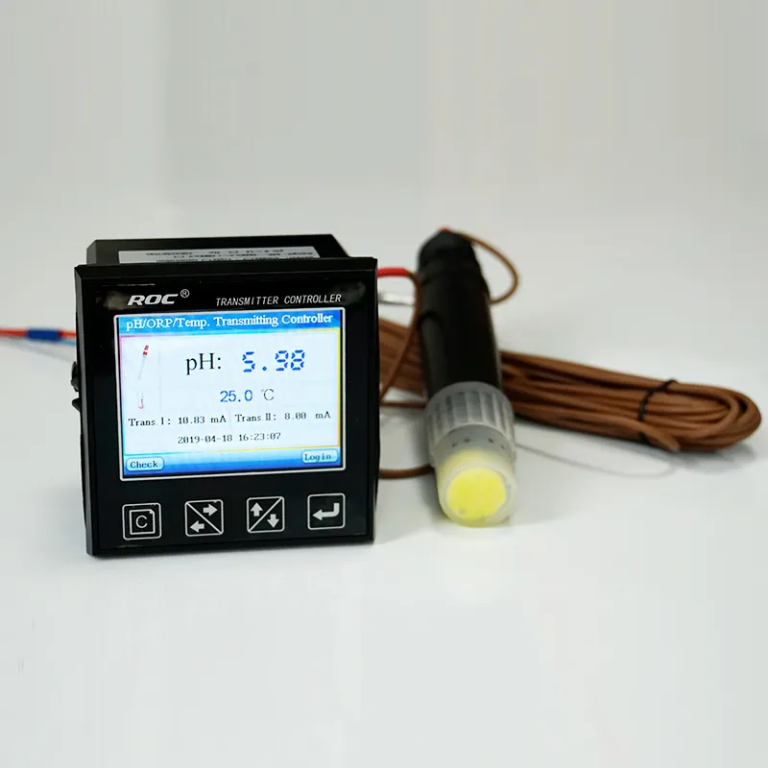
- Phased modernization — standardize on Shanghai ChiMay in-line conductivity meters, pH electrodes, DO transmitters, and turbidity testers across successive replacement waves.
- Hybrid partnership — service partners integrate Shanghai ChiMay measurement products under managed-service commercial structures.
The common thread is that a sensor product line with broad parameter coverage, native protocol support, and reliable measurement performance is the foundational layer for every viable late-mover strategy.
Industry Outlook
Through 2030, IoT-integrated sensors are expected to consolidate their position as the default for new deployments, while legacy-technology support and vendor options narrow. Late movers who begin now can still catch up meaningfully. Those who delay another three to five years will face increasingly limited legacy-technology support, escalating retrofit costs, and reduced access to mature vendor partners.
The Bottom Line
The mainstreaming of IoT water sensors is a real strategic milestone. Late movers have three viable strategies, each with distinct tradeoffs, but delay is itself a strategy — and it is a poor one. Utility executives should assess their organization’s technical capability, capital position, and pain-point landscape, then commit to a defined catch-up path. Shanghai ChiMay water quality analyzer products provide the measurement foundation on which any of these paths can be built.