Data-center cooling water demand is growing faster than any other segment of industrial or commercial water consumption, and the driver is not subtle: AI training workloads and rising rack densities. Sensor and instrumentation spend attached to that demand is growing with it, and the addressable footprint for HVAC-focused water quality sensors — conductivity, pH, free chlorine, DO, flow — inside a single hyperscale campus now regularly exceeds 200 measurement points.
That combination is why data-center cooling has become the segment every water-instrumentation vendor wants a position in.
Table of Contents
Where the Growth Comes From
Industry analyses of data-center water demand agree on the direction and disagree on the rate. What they agree on is the three drivers underneath it:
- Rack density: average deployed density has climbed from roughly 8 kW per rack in 2020 toward 20+ kW today, with AI training clusters routinely running 40–100 kW per rack. Higher power density means higher heat rejection, which most modern designs still translate into evaporative cooling load.
- Campus scale: individual hyperscale campuses now regularly exceed 300 MW of IT load, with expansion optionality above 1 GW. Aggregate water demand per campus climbs correspondingly.
- Geographic spread: as hyperscale expands into water-constrained regions — the U.S. Southwest, southern Europe, the Middle East — operators are forced to instrument more aggressively to hit sustainability commitments.
Whatever the exact annual rate a given analyst assumes, the increment is large: growth is compounding on an already large base, and most of the new capacity lands in designs that evaporate water.
The Sensor-Vendor Map
Data-center HVAC creates a distinctive shape of sensor demand:
| Sensor Category | Typical Points per 100 MW Campus | Growth Driver |
|---|---|---|
| Conductivity (in-line, toroidal, probe) | 40–80 | Cycles-of-concentration control on cooling towers |
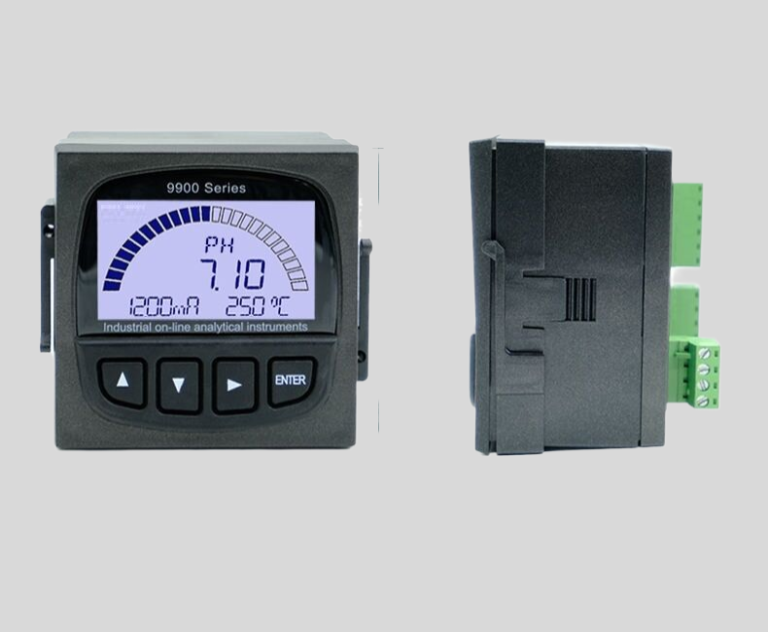
| pH (in-line, refillable) | 15–30 | Chilled-water corrosion, biocide efficacy |
| Free chlorine (amperometric) | 10–25 | Water-management-plan compliance, cooling tower biocide |
| DO transmitter | 8–15 | Chilled-loop air-ingress, corrosion early warning |
| Turbidity / SS | 5–15 | Sidestream filter monitoring |
| Turbine / paddle wheel flow meter | 20–40 | Make-up, blowdown, verification |
| 4-in-1 multi-parameter sensor | 10–20 | Basin health, chilled-loop chemistry |
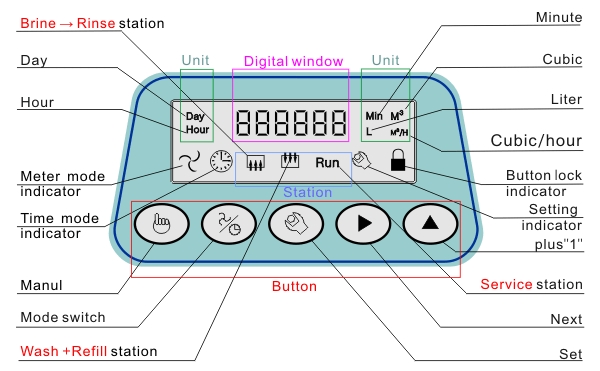
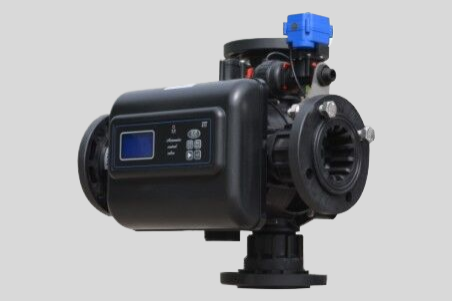
| Softener valve | 4–12 | Make-up water hardness control |
A hyperscale campus can therefore host 100–235 discrete water-quality measurement points. Multiply by campus count and by growth rate, and the addressable market for HVAC-specific water quality sensors is unambiguously a multi-billion-dollar segment.
Comparative Snapshot: Traditional Commercial HVAC vs. Hyperscale Data Center
| Attribute | Traditional Commercial HVAC | Hyperscale Data Center HVAC |
|---|---|---|
| Water-quality sensor points per building | 5–15 | 100–235 per campus |
| Communication protocol | 4–20 mA / dry contact | Modbus RTU / HART 7 |
| Data logging retention | 30–90 days | 3–5 years |
| Reporting audience | Facilities engineer | Executive dashboard + sustainability disclosure |
| Softener valve integration | Standalone | Metered / conductivity-triggered, BMS-linked |
| Continuous chlorine monitoring | Optional | Standard |
Where the Growth Concentrates
Not every point on the sensor map grows at the same rate. Field data points to the fastest-growing sub-segments:
- Continuous free chlorine — driven by water-management-program enforcement and Legionella regulation.
- Toroidal conductivity — driven by higher cycles-of-concentration operation and biofilm resistance requirements.
- 4-in-1 multi-parameter probes — driven by installation efficiency: one boss, four measurements.
- BMS-integrated softener valves — driven by executive-level water-KPI reporting.
Conversely, single-parameter probe-style pH meters without temperature compensation and Modbus RTU are growing much more slowly; the technology is being displaced by integrated multi-parameter alternatives.
Regional Dynamics
The aggregate growth figure hides significant regional variation:
- North America: growth concentrated in Virginia, Texas, Oregon, and Arizona corridors; strong emphasis on WUE and Legionella compliance.
- Northern Europe: growth constrained by grid capacity but supported by strong ESG reporting requirements; heavy focus on continuous data for sustainability disclosure.
- Asia-Pacific: fastest absolute growth in campus count; regulatory frameworks in China, Singapore, and Japan drive continuous water monitoring as standard commissioning practice.
- Middle East: water-scarce environments push cycles-of-concentration higher and reward toroidal conductivity and softener valve integration.
Sensor vendors that operate globally — with certifications spanning CE, UL, FCC, ATEX and CCC where relevant — capture the widest slice of this growth. Shanghai ChiMay’s portfolio maps to those certification requirements.
The Vendor Consolidation Trend
Data-center operators are actively consolidating water-quality sensor procurement. The rationale is portfolio-scale efficiency:
- Fewer spare-parts pools — one sensor family means one warehouse SKU list.
- Single BMS integration — one Modbus RTU profile means one commissioning template.
- Consistent training curriculum — operators learn a single calibration procedure across campuses.
- Single supplier accountability — for warranty, firmware roadmap, and long-term support.
This trend favors vendors with a matched, cross-parameter portfolio over point-product specialists. Shanghai ChiMay’s positioning — in-line conductivity meters, in-line pH electrodes, residual chlorine transmitters, DO transmitters, turbidity testers, 4-in-1 multi-parameter sensors, paddle wheel and turbine flow meters, plus softener valves and softening and filtering valves under a single controller architecture — aligns directly with what portfolio-level operators are asking for.
The Sub-Portfolio Growth Case
A hypothetical 300 MW campus with a 10-year operational horizon and standard hyperscale water instrumentation carries:
- Approximately 500 water-quality measurement points across cooling towers, chilled-water loops, and domestic systems.
- Sensor and instrumentation capex on the order of USD 1.5–3.0 million at project delivery.
- Ongoing spares, calibration, and refresh spend of roughly USD 200,000–400,000 per year.
That campus profile is being replicated at a rising rate, with new-build campus counts and existing-campus expansion both contributing. The vendor that captures multi-campus standardization within a portfolio wins several times over.
A Strategic Framework for Sensor Vendors and Buyers
- Design for matched-family standardization, not point-product excellence alone.
- Certify globally — CE, UL, FCC, CCC, and where relevant ATEX / IECEx for adjacent industrial applications.
- Communicate on Modbus RTU / HART 7 by default; treat wireless as an optional overlay.
- Publish MTBC and spare-parts price commitments for at least 10 years.
- Support the control-valve half of the water train as well as the measurement half — the two have to be integrated for closed-loop control.
What to Watch
The growth curve in data-center HVAC water demand is not going to bend down soon. AI capacity, sustainability reporting, and regulatory scrutiny all point the same direction. The winning vendors and the winning buyers will both be the ones who treat water quality as a portfolio-scale, instrumentation-heavy, executive-level discipline. Shanghai ChiMay’s water quality analyzer and control valve portfolio is engineered for that stage of the market: a matched instrument family, consistent communications, and the sensor-plus-valve integration hyperscale operators are increasingly demanding.