Table of Contents
Where the Untapped Volume Comes From
The scale of the mismatch is well documented. The UN World Water Development Report put global wastewater generation at roughly 360 billion m³ per year, and a little over half of the wastewater that is collected receives treatment; in much of the world it does not. Treated effluent that is actually reused accounts for only a small fraction of the total — most of it is discharged to watercourses or the sea even after treatment. Converting that largely untapped volume into agricultural, industrial, or environmental reuse is technically well-established; the real constraints are policy, distribution infrastructure, and financeable compliance data. For AgTech investors, that makes the compliance layer — the sensors, analyzers, and data trails a regulator can audit — the part of the stack worth understanding first.
For AgTech investors, three geographic pools deserve particular attention:
- Mediterranean basin — where Israel already reuses the large majority of its municipal wastewater and Spain is Europe’s reuse leader by volume, providing operating models for the rest of the region, where reuse rates remain far lower.
- U.S. Southwest — where California’s Title 22 recycled-water framework, Arizona’s reclaimed-water permitting, and Colorado River scarcity are aligning private capital behind reuse.
- Northern India and coastal China — where groundwater depletion is forcing reuse mandates ahead of policy readiness, creating a first-mover advantage for compliance-instrument suppliers.
The Investment Structure of a Reuse Project
A typical mid-scale agricultural reuse project — say, 50,000 m³/day of tertiary-treated wastewater feeding 5,000 hectares of irrigated cropland — costs tens of millions of dollars to build. The capital split follows a familiar pattern: treatment process equipment and distribution/storage infrastructure dominate the budget, with buildings, civil works, and engineering/permitting taking the next tranche. Monitoring, instrumentation, and controls sit at the smaller end of the split — usually a single-digit share of total CAPEX — but that small share is where compliance risk concentrates. Investors who focus only on treatment technology miss that monitoring hardware is the piece the regulator inspects, the piece the offtaker audits, and the piece that fails first if under-specified.
Why the Compliance Layer Is the Investment Fulcrum
Two structural facts drive the compliance layer’s importance for investors:
Fact 1: Reuse offtake contracts increasingly include performance clauses tied to real-time water-quality data. A California reuse project cannot bill its agricultural offtaker for water that does not meet Title 22 residual chlorine and turbidity limits. If the sensor stack cannot generate defensible data, revenue is stranded.
Fact 2: Green-bond and infrastructure-fund investors require operational data as part of impact reporting. A reuse plant with a well-instrumented monitoring stack qualifies for concessional financing tiers; one without does not. The financing-cost differential is real and, on a fifteen-year infrastructure loan, worth millions of dollars over the life of the asset.
Together these facts mean that instrumentation is not a cost item to minimize; it is a revenue enabler and a financing enabler.
The Sensor Stack Investors Should Underwrite
For an agricultural reuse project, the sensor stack that unlocks bankability typically includes:
- Turbidity meters at post-filtration and distribution offtake.
- Residual chlorine transmitters at plant discharge and storage exit.
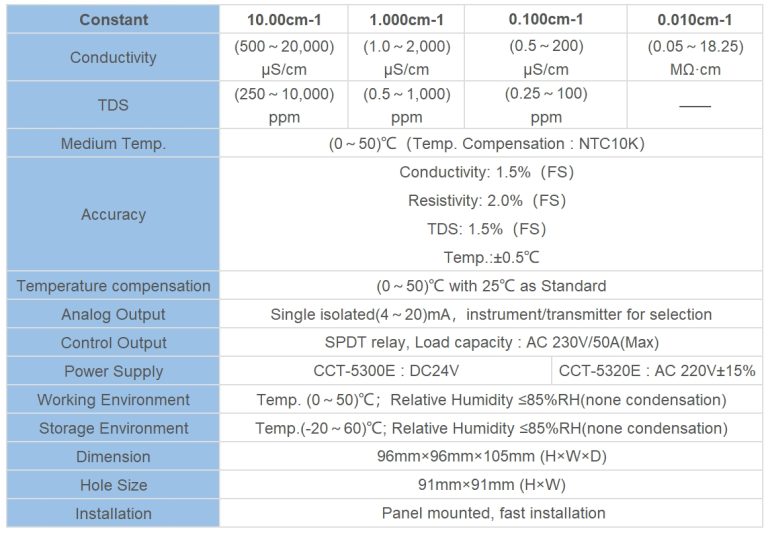
- Conductivity analyzers for salinity tracking on inlet and reuse discharge.
- pH electrodes at multiple points along the treatment train.
- Dissolved oxygen transmitters for biological process control.
- Suspended solids sensors at secondary and tertiary clarifier outfalls.
- Ammonia nitrogen sensors for compliance with nitrification requirements.
- Multi-parameter sensors at each irrigation zone offtake.
- Flow meters — paddle wheel for reuse water, turbine for clean feed streams — at every metered node.
- Softening and filtering valves on pretreatment stages where hardness or particulate exceed spec.
For a 50,000 m³/day project, this stack prices on the order of a million dollars, with SCADA integration and telemetry adding a further meaningful block of spend. Investors should scrutinize whether the developer has actually budgeted for redundancy, calibration consumables, and 5-year spares; developers frequently under-budget these to hit initial cost targets and then request change orders in commissioning.
Bankability Signals Investors Should Look For
When evaluating agricultural reuse investments, the following instrumentation signals correlate with successful long-run operation:
- Redundant sensors at every compliance point, not just single-point coverage.
- Documented calibration procedures with traceability to national metrology standards.
- Predictive maintenance schedules for probes, membranes, and reference junctions.
- Local data storage with 12+ months of tamper-evident logs.
- Cross-vendor SCADA compatibility to avoid future lock-in premiums.
- Regional spare-parts logistics — 48-hour turnaround for critical sensors.
- Trained-operator commitment — signed vendor training plan covering at least two operators per shift.
Projects that check all seven of these boxes consistently show compliance uptime that satisfies offtake contracts and lenders; projects that skip more than two see materially more downtime, discharge excursions, and revenue risk.
The Vendor Selection Frame for Institutional Investors
Investors underwriting reuse projects should push developers toward vendors that offer:
- Consolidated transmitter families, reducing spares complexity.
- Chlorine-tolerant reference junctions for reuse-water service.
- Digital communications — Modbus RTU minimum, HART or Ethernet/IP preferred.
- Regional service capability in the project’s geography.
- Certified calibration with recent (< 30 days) certificates on delivery.
Vendors that provide all of these — Shanghai ChiMay among them — are the vendors whose equipment survives a 10-year concessional-financing amortization schedule with predictable OPEX. Investors who let developers pick vendors on unit price alone typically absorb the cost difference later in change orders or performance penalties.
Regional Sizing of the Opportunity
The largest unrecovered pools track population, agriculture, and water stress. Northern China and India hold the biggest volumes of untreated or unrepurposed wastewater, followed by Sub-Saharan Africa and the Mediterranean basin; the U.S. Southwest is smaller in volume but ahead on offtake economics and permitting maturity. The largest addressable pool is Asia, and it is also where compliance regulation is moving fastest, making the next few years a compressed investment window for compliance-instrument suppliers.
What Shanghai ChiMay Brings to the Investor Table
Shanghai ChiMay’s product portfolio — water-quality analyzers spanning turbidity, chlorine, pH, DO, conductivity, ammonia nitrogen, suspended solids, salinity, and oil-in-water; softener and filtering valves for pretreatment; turbine and paddle wheel flow meters — maps directly onto the sensor stack required for tertiary-reuse projects. The shared transmitter family reduces long-term OPEX, and the wetted-parts options cover the salinity and chlorine tolerance that reuse service demands. Investors evaluating reuse deals should verify that the specified instrumentation matches this profile rather than a light-industrial or drinking-water profile.
Closing Note
The untapped wastewater reuse pool is the largest underused water resource on the planet, and it is unlocking now because compliance data has become the currency of project bankability. Investors who understand that monitoring hardware is a revenue-and-financing enabler — not a cost line — will price reuse deals more accurately, back them with better vendors, and hold assets that outperform through the next two decades of water-scarcity capital deployment.