The global water recycle and reuse market is valued at USD 20.59 billion in 2026 and is projected to reach USD 35.04 billion by 2031 at an 11.22% CAGR (Mordor Intelligence, 2026), placing it among the fastest-growing segments of the broader water treatment industry. Regulation is the main demand engine: China’s wastewater resource utilization policy sets binding reuse targets for water-scarce cities, the EU Water Reuse Regulation has applied since June 2023, and in the United States the EPA’s Water Reuse Action Plan keeps pushing reuse up the industrial agenda. Meanwhile the water-positive pledges of Amazon, Microsoft, Meta, Google, and Apple are building a second, private-sector demand layer for verified reuse data. Board engagement with water reuse is no longer optional for water-intensive industries — it is a risk management issue that touches compliance, license to operate, and long-term cost structure.
Table of Contents
The Market Signal: From Niche to Mainstream Capital Allocation
Water reuse was once a niche technology deployed only in water-scarce regions like the Middle East or coastal California. That framing no longer matches reality. The reuse market is growing across geographies and industrial sectors, driven by regulatory pressure, freshwater scarcity, and corporate ESG commitments.
For board members, the question is not whether water reuse will affect their industry — it already is — but whether the company’s strategy, capital allocation, and risk management frameworks are positioned to respond.
The USD 35.04 billion market projection for 2031 signals more than a revenue opportunity for technology providers. It marks a structural shift in how water-intensive industries — food and beverage, semiconductors, textiles, power generation, mining — treat water as a resource. Companies that run water as a single-pass input face rising costs and regulatory exposure; companies that design water into a circular loop gain cost advantages and stakeholder confidence.
Three Regulatory Regimes Reshaping the Market
Three major frameworks are driving the current wave of reuse investment:
China’s wastewater resource utilization targets (14th Five-Year Plan period):
Under the January 2021 Guidance on Promoting Wastewater Resource Utilization issued by the NDRC and MOHURD, prefecture-level and above cities facing water scarcity must reach at least 25% reclaimed water utilization by 2025, with the Beijing–Tianjin–Hebei region targeting 35% or more. This is not a voluntary aspiration — it is backed by central environmental inspection mechanisms. For industrial facilities in these cities the implication is direct: process water that can be recycled must be monitored, documented, and demonstrated to meet reuse quality standards. On the market side, DataM Intelligence puts China-relevant industrial water reuse and recycling at USD 19.20 billion in 2025, growing to USD 49.13 billion by 2035 at a 9.9% CAGR, with Asia-Pacific the fastest-growing region.
EU Water Reuse Regulation (Regulation (EU) 2020/741):
Applicable since 26 June 2023, the regulation sets four reuse quality classes for agricultural irrigation, with Class A — the strictest — covering all food crops eaten raw. European food and beverage companies that source from irrigated agriculture now have to verify that water applied to their supply-chain fields meets these standards, which creates demand for reuse monitoring instruments across the agricultural value chain.
United States — EPA Water Reuse Action Plan:
The EPA launched the National Water Reuse Action Plan (WRAP) in February 2020 and relaunched it as WRAP 2.0 in April 2026. It is a voluntary, collaborative framework rather than a numeric federal mandate, but it channels funding and policy attention toward reuse — including industrial applications — and it is accelerating adoption in states that previously had limited reuse activity, particularly in the Midwest and Southeast.
For boards of companies operating in any of these three jurisdictions, the regulatory environment creates both compliance obligations and strategic opportunities. The question is whether the company treats reuse as a compliance cost to be minimized or a capability to be built.
Corporate Water Stewardship: The Private-Sector Demand Layer
Beyond government mandates, the largest water-consuming corporations are generating their own demand for reuse capability. The water stewardship commitments of Amazon, Microsoft, Meta, Google, and Apple all include replenishment and recycling targets that require verified data on water recovery rates and reuse volumes.
CDP Water Security disclosure scoring rewards verifiable water management evidence over self-reported annual figures, and uptake of the Alliance for Water Stewardship (AWS) Standard 2.0 keeps accelerating — certified sites are expected to demonstrate monitoring of water quality parameters at withdrawal, use, and discharge points.
For boards, the implication is that reuse instrumentation is becoming part of the corporate reporting infrastructure, not just the process control infrastructure. Data from reuse sensors feeds ESG reports, CDP disclosures, and investor presentations, and the credibility of that data directly shapes how the company is read by investors, customers, and regulators.
What Boards Should Ask Their Management Teams
Board members evaluating their company’s positioning in the water reuse market should ask:
- What is our current water reuse rate, and how does it compare to industry peers? Companies that cannot answer this question are already behind.
- Do we have continuous monitoring in place, or do we rely on grab sampling? Continuous monitoring is increasingly the practical requirement for regulatory compliance and ESG reporting.
- What is the capital plan for reuse infrastructure over the next five years? At an 11.22% CAGR, competitors investing now will hold cost and compliance advantages within three to five years.
- How does our reuse strategy align with our ESG reporting commitments? If the company has made net-water or water-positive pledges, the monitoring infrastructure has to be in place to verify progress.
- Are we exposed to jurisdictions where reuse mandates are tightening? China, the EU, and the USA are all moving in that direction, and companies operating there face compliance deadlines that require capital allocation decisions today.
The Role of Monitoring Technology in the Reuse Value Chain
The reuse value chain — collection, treatment, distribution, end use — depends on continuous water quality monitoring at every stage. The global water quality sensor market, valued at USD 5.17 billion in 2026 and projected to reach USD 10.17 billion by 2035 at a 7.8% CAGR (Market Research Future, 2026), reflects that instrumentation demand.
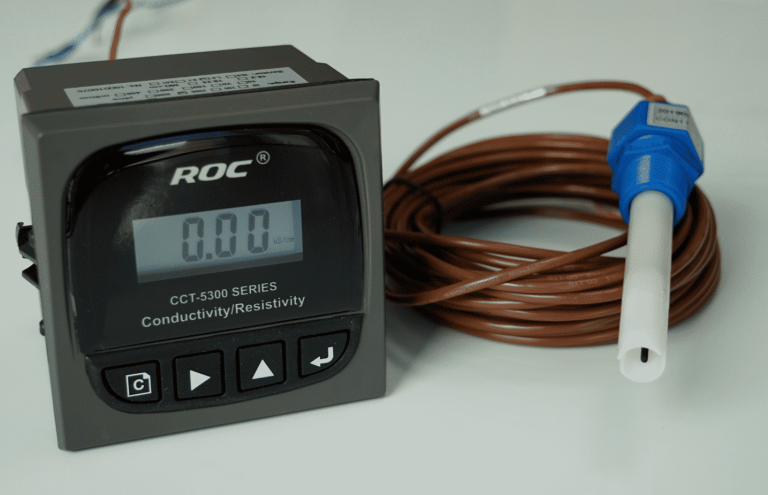
Shanghai ChiMay supplies the sensor and analyzer platforms that cover reuse monitoring end to end: multi-parameter sensors for water quality characterization, conductivity analyzers for dissolved solids tracking, COD sensors for organic load verification, turbidity testers for particulate monitoring, and residual chlorine transmitters for disinfection management.
For boards evaluating technology partnerships, the practical question is whether the monitoring provider can support the full reuse value chain from one integrated platform, rather than stitching together single-parameter instruments from several suppliers.
Strategic Implications for Board Discussion
The water reuse market’s growth from USD 20.59 billion to USD 35.04 billion over the next five years rests on binding regulatory mandates, corporate commitments, and capital plans already announced by major utilities and industrial companies — it is not a speculative forecast.
Boards that engage with water reuse strategy early position their companies for cost savings, compliance readiness, and stakeholder confidence. Boards that defer the conversation risk meeting the mandates unprepared, after competitors have already built the reuse capability.
Shanghai ChiMay’s role is to provide the monitoring infrastructure that makes reuse operations verifiable, compliant, and defensible — the data foundation boards need for informed decisions on water reuse investment.